Saudi Pipeline Shutdown Puts 4% of Global Oil Supply at Risk
A prolonged halt on the East-West pipeline would test Riyadh’s export strategy, Aramco’s resilience and the market’s reliance on Red Sea routes.
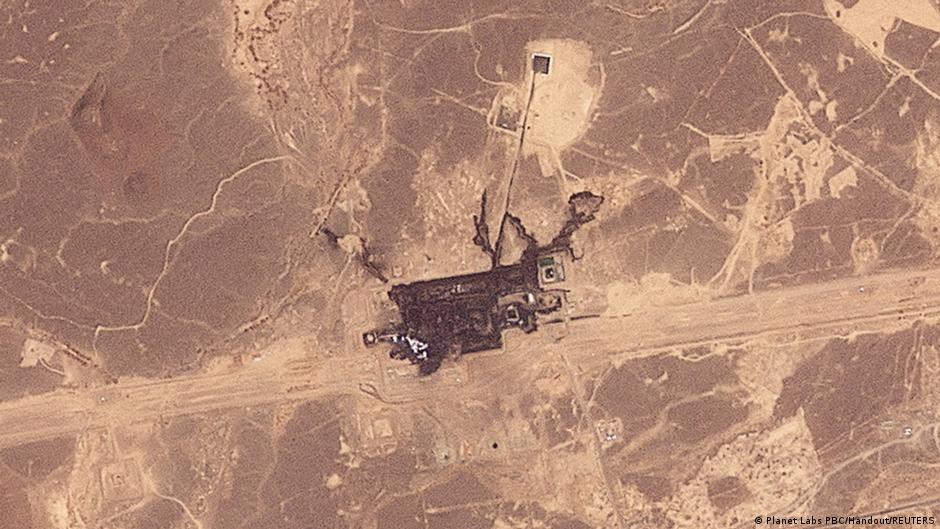
A prolonged shutdown of Saudi Arabia’s East-West oil pipeline could cut global oil supplies by 4 percent, according to Reuters, citing informed sources in the oil market. The duration of repairs remains unclear after the pipeline was stopped following a drone attack attributed to the Houthis.
For Riyadh, the incident is more than an operational disruption. The East-West line is a central asset in Saudi Arabia’s export strategy, linking the kingdom’s main oil fields in the east with the Red Sea port of Yanbu. That route allows Saudi Arabia to ship millions of barrels a day without using the Strait of Hormuz, where traffic has been restricted by Iran.
If the pipeline is not restored in the coming days, Saudi Arabia could face a shortage of oil stocks available for export, Reuters reported on Sunday, September 13. Market sources cited by the agency said the result could be a 4 percent decline in global supply, a significant shock for refiners, traders and governments already watching security risks around key energy corridors.
Saudi authorities have not provided full information on the scale of damage to the pipeline after the drone strikes or on the timing for resuming oil flows. The pipeline was suspended on September 11. The Saudi energy ministry said at the time that the shutdown had been ordered as a “precautionary measure” after drones launched from Iraqi territory struck the Riyadh and Medina provinces.
Saudi officials have described the stoppage as precautionary, but the market focus is now on how long the repair window lasts and how much export flexibility Riyadh retains.
A Strategic Route Under Pressure
The East-West pipeline runs for 1,200 kilometers and has long served as a strategic bypass for Saudi crude exports. In business terms, it is a hedge against chokepoint risk: when tanker movement through the Strait of Hormuz is constrained, Riyadh can reroute crude westward toward the Red Sea and maintain access to international buyers.
That flexibility has become more important since the start of the war against Iran. Saudi Arabia sharply increased use of the pipeline, and by June exports through the route had reached nearly 8 million barrels per day, according to the International Energy Agency. That scale underscores why even uncertainty around the pipeline’s availability can move market expectations.
The latest stoppage also highlights a broader management challenge for Saudi Arabia and Saudi Aramco: the kingdom’s export infrastructure is increasingly exposed across multiple theaters. The East-West line was designed to reduce reliance on the Strait of Hormuz, but the Red Sea route has faced its own security pressures. In recent weeks, capacity on the route has fallen because of Houthi attacks on Saudi tankers in the Red Sea.
In August, around 2.5 million barrels per day were shipped through Yanbu, the lowest level since 2013, according to the IEA’s latest monthly report. That drop suggests the problem is not limited to one pipeline incident. It points to a narrowing of Saudi Arabia’s logistical options at a time when buyers, insurers and shipping companies are already pricing geopolitical risk into energy flows.
Repair Timeline Becomes a Market Variable
The corporate and market implications now depend heavily on the repair schedule. One Reuters source said repairs could take five to six weeks. Another source said the work could be completed faster and that pumping might resume before repairs are fully finished.
That range matters. A brief interruption would be disruptive but manageable, especially if Saudi Arabia can draw on inventories or stagger flows. A multi-week outage would put more pressure on export planning, customer commitments and Saudi Aramco’s ability to sustain confidence among long-term buyers. It would also sharpen attention on spare capacity, storage levels and the resilience of alternative shipping routes.
The episode may also influence how investors and industry executives view infrastructure risk across the Gulf. Saudi Aramco restored the East-West pipeline quickly after an attack in April, demonstrating operational capacity and crisis response. The current uncertainty, however, comes against a more strained regional backdrop, with the Hormuz route constrained by Iran and Red Sea tanker movements disrupted by Houthi attacks.
For competitors, any prolonged Saudi disruption could shift short-term supply dynamics. Producers able to move barrels through less exposed routes may find stronger demand from buyers seeking continuity. But the effect would depend on how quickly Riyadh restores the pipeline and whether Saudi export volumes from Yanbu can recover from August’s reduced levels.
For Saudi management, the immediate task is technical repair. The larger strategic question is how to preserve export reliability when both the Hormuz bypass and the Red Sea corridor face heightened risks. The East-West pipeline remains one of the kingdom’s most important energy assets, but the latest shutdown shows that diversification of routes does not eliminate vulnerability; it redistributes it.
Until Saudi authorities provide clearer information on the damage and restart timing, oil-market participants are likely to treat the pipeline outage as a material supply risk. A 4 percent potential hit to global oil supplies gives the incident significance beyond Saudi Arabia’s borders, making the repair timeline a corporate, geopolitical and market issue at once.